
Consumers Will Let AI Research but Not Yet Buy: What the Trust Gap Means for Checkout Design and Merchant Controls
If you run ecommerce, you are being asked to plan for agent-led purchasing. The forecasts are loud, the product launches are frequent, and the data that would tell you how much of it will be real is thin. One finding does appear in the reporting we hold: consumers seem more willing to let AI help them research a purchase than to let it complete one. Our view is that this gap is the most useful thing a merchant can design around, because it is a constraint on how fast delegated purchasing can grow and it points at specific controls. It is also a finding we should hold lightly, for reasons we set out below.
This is a market-outlook piece built on limited evidence. Where the evidence runs out, we say so.
What the evidence shows, and what it does not
Start with what is actually on the table.
The survey finding. Reporting from October describes consumer surveys indicating that willingness to use AI to research a purchase outpaces willingness to let it complete the purchase. The surveys appear in a release from Wildfire Systems, a vendor, and in coverage by Forkast News. The evidence base is therefore a company's own research, reported through news coverage. It points in a direction. It is not an independent, peer-reviewed study. We have no sample sizes, question wording or percentages from the reporting we hold, and we are not going to supply any.
It is not UK data. The survey and download data in the reporting are from the United States or North America. One of the reports ran on a UK finance site, which can make it look British. For a UK merchant, the position is that this is an American signal, and UK consumer evidence would need to be found before anyone treats it as a UK finding.
It is one signal, not a trend line. The same theme appears in the market commentary on trust and liability. That is consistent with the survey, but it is not independent confirmation, because the commentary is partly about the same question from a different angle.
So the claim we are prepared to make is narrow: there is vendor-authored survey evidence, from North America, that points to a gap between letting AI research and letting AI pay. The claim we are not prepared to make is any statement about how large the gap is, how fast it is closing, or whether UK consumers behave the same way.
What the adoption signals do and do not tell you
Alongside the survey, three other signals tend to be quoted in the same breath. Each is worth reading carefully.
An executive says activity "went vertical". Stripe's president has said that agentic-commerce activity went vertical from September, as reported by Payments Dive, with no figures disclosed. This is an unquantified claim from the executive of a company that sells payments infrastructure. It may well be accurate. It cannot tell you what share of purchases are agent-led, and it does not distinguish between agents researching, agents building baskets and agents paying.
A consumer assistant is downloaded quickly. Meta's Muse assistant passed 10 million downloads in the United States and Canada in 35 days, according to Sensor Tower data reported by PYMNTS. That shows an assistant can reach a large audience quickly through a platform with an existing base. A download is not active use, and it is certainly not a purchase. The data covers North America only.
Search demand is rising. Keyword data show US demand for "agentic commerce" about 2.8 times higher than a year earlier, and UK demand about 3.3 times higher, with the US market roughly four times the size of the UK. This is useful in a limited way. It suggests people are looking for explanations of the term. It says nothing about consumers buying. Interest in a phrase is not delegated spending.
Read together, these signals describe attention and distribution growing quickly. The survey finding adds that the step from attention to delegated payment is the hard one. That is the pattern a merchant should plan for, with the caveat that each piece comes with its own weaknesses.
Why a trust gap between research and payment is plausible
We can say why the gap would make sense, as analysis rather than reported fact.
Research is reversible and cheap. If an assistant summarises reviews, compares specifications or suggests three options, the cost of a wrong answer is a few minutes. The person remains in control of the decision and the money.
Payment is neither. A wrong purchase costs money, may need a refund process and can raise a dispute. When the buyer is an agent, an additional question appears: if the agent bought the wrong thing, who is responsible? The October reporting calls authorisation and liability the dominant agentic-commerce theme for the third review period running. A large US bank has reportedly blocked outside agents from direct access to customer accounts and backed open-banking routes instead. The FCA has published examples of good and poor AI practice and, as the reporting describes it, is applying existing frameworks such as the Consumer Duty and senior-manager accountability rather than writing new rules for agents.
None of that is consumer survey data. But it shows that institutions are treating delegated payment as a different kind of risk from research, which is consistent with consumers doing the same.
What this means for checkout design
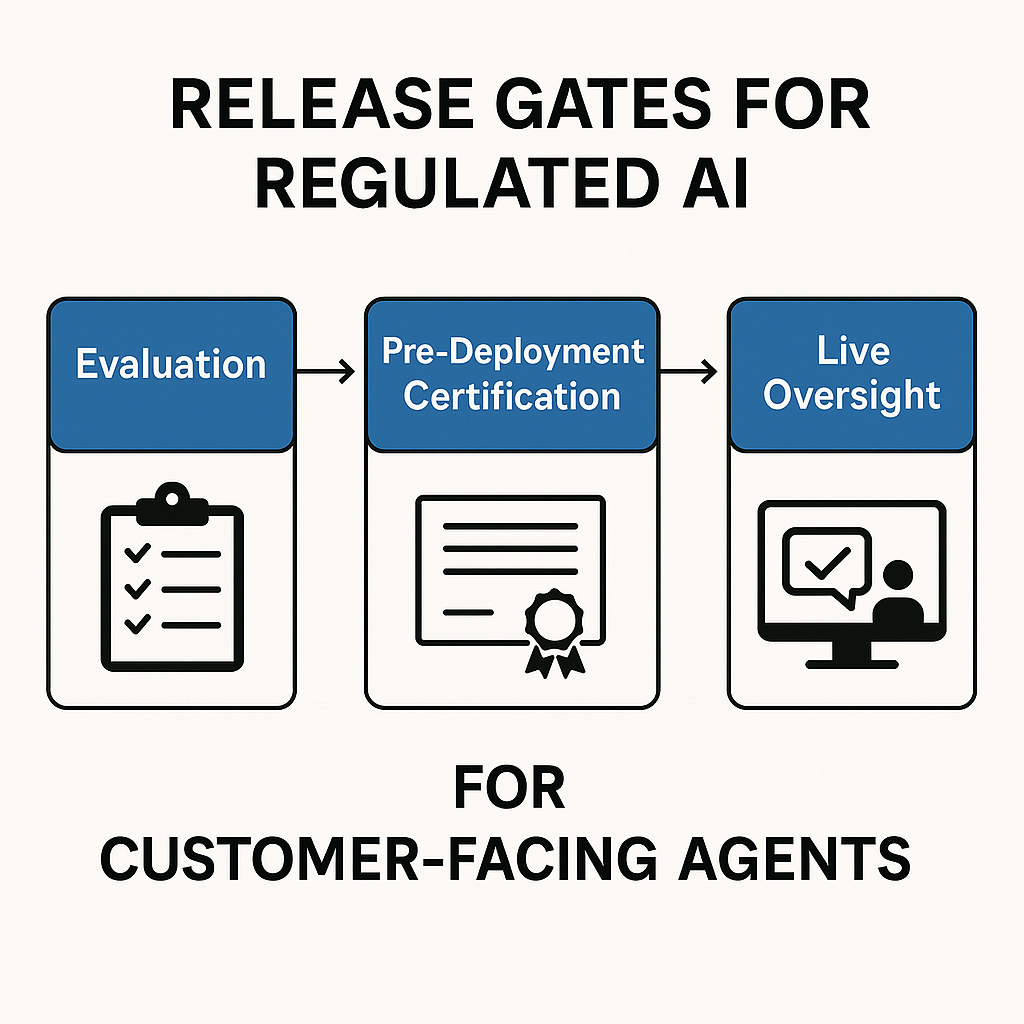
If the gap is real, checkout should not be designed on the assumption that a consumer who happily asks an assistant for recommendations will also happily hand it a card. The design response is to make delegation graduated, so that the consumer gives away as much authority as they are comfortable with and no more.
Separate discovery from commitment
Let the agent do the research, the shortlisting and the basket-building, and treat the moment of payment as a distinct step with its own interface. This sounds obvious, but many designs blur the two, so that a conversation that began as a question ends in a charge. A clear boundary between "I have found something" and "I am paying for it" is the first control.
Use a confirmation step that carries real information
A confirmation step is only reassuring if it shows what matters: what is being bought, from whom, at what total price, to which address, and under what returns terms. A bare "Confirm?" button trains people to click without reading. For higher-value or unusual purchases, the confirmation should be harder to skip, and the reason for the extra friction should be explained.
Give the consumer spend limits they set themselves
A limit set by the consumer is a different thing from a limit imposed by the merchant. A consumer who can say "up to this amount per purchase, and only from these retailers" is delegating within a boundary they understand. In practice that means per-transaction ceilings, merchant or category restrictions and a way to see and revoke what has been granted. These are the same kinds of control that appear in business spend management, applied to a consumer.
Make the agent identifiable to the merchant
From the merchant's side, an agent buying on behalf of a customer needs to be recognisable and attributable. The reporting notes that tooling for agent identity and delegated authority multiplied within a single week in October, with no standard emerging. The merchant does not need to choose a standard to act on the principle: know which agent is asking, on whose authority, and keep a record of it.
Plan for the dispute before it arrives
A delegated purchase that goes wrong needs a defined path: who reviews it, what evidence is kept and how the refund is handled. Keep the record of what the consumer authorised, what the agent proposed and what was bought. If the path is not defined before launch, it will be invented under pressure after the first complaint.
What merchants should control
The consumer controls above have merchant-side counterparts. They are easier to build than to explain to a board, so we set them out plainly.
- Decide what you will accept from an agent. Choose which agents, if any, may complete a purchase, and under what conditions, rather than accepting everything that presents itself.
- Apply your normal risk checks. An agent-originated order should still pass your fraud, address and payment checks, with extra scrutiny where identity cannot be established.
- Treat high-risk categories differently. Items that are expensive, regulated or hard to refund justify a stronger confirmation step than a low-value repeat purchase.
- Measure the gap yourself. Track how often agent-assisted sessions end in a purchase compared with other sessions, and how often confirmed agent purchases are returned or disputed. Your own data will tell you more than any survey, and it will be about your customers.
How to read forecasts of agent-led purchasing
The practical question for a retail or platform leader is how much weight to give the forecasts, so a short guide.
Ask what the number measures. A download, a search volume, a session in which an agent was involved and a completed, paid order are very different things. Most of the evidence we have sits at the first two.
Ask who produced it. A vendor survey or an executive statement is not worthless, but it is produced by people with an interest in the market growing.
Ask where it was measured. North American data may or may not translate to the UK. Different payment habits, regulation and consumer protections could all change the picture, and we do not have evidence either way.
Ask what would change your mind. If, in six months, your own data shows agent-assisted sessions converting at rates close to other sessions, the trust gap is narrowing for your customers. If they show frequent abandonment at the payment step, it is not. Decide that in advance.
Where Innovify fits
Innovify is a technology partner with deep expertise in banking, financial services, fintech and insurance. We help mid to large businesses build AI-native products, modernise their technology stack and launch fintech products, and we design compliance in from day one.
The controls in this piece, such as graduated delegation, a meaningful confirmation step, consumer-set limits and a dispute path, are the kind of thing that is better tested with real users than argued about in a meeting. Our Agentic Commerce & Payments work looks at how delegated purchases are authorised, limited and recorded, and Innovify AI Labs lets enterprise teams run several proofs of concept in parallel, test with real users and finish with a business case ready for funding. If you want to find out where your own customers draw the line between research and payment, talk to us about a first test.
FAQ
Will consumers let an AI agent complete a purchase?
The evidence we hold suggests many are more willing to let AI research than to let it pay, but it is thin. It comes from a vendor-authored survey and related coverage, is North American and gives no figures we can quote. We would not forecast UK behaviour from it.
Why do consumers trust AI to research but not to buy?
Research is reversible and inexpensive, while a purchase involves money, possible disputes and a question of who is responsible if the agent is wrong. That reading is our analysis, but it is consistent with the weight that authorisation and liability carry in the October reporting.
Is agentic commerce growing quickly?
Signals of attention are growing quickly, but they are not measures of completed purchases. Meta's Muse reached 10 million downloads in North America in 35 days according to Sensor Tower, and search demand for "agentic commerce" is up year on year in the US and UK. Downloads and searches are not purchases.
What checkout controls help bridge the trust gap?
Four controls help most: a clear separation between discovery and payment, a confirmation step that shows price, seller and terms, spend limits the consumer sets, and an identifiable agent with a record of its authority. These reflect our analysis rather than tested results, so they should be validated with your own customers.
Does UK evidence exist on consumer trust in agent checkout?
The reporting we hold does not include UK consumer survey data on this question. The survey and download figures are US or North American. A UK merchant should seek UK evidence, or gather its own, before relying on the finding.
How should merchants plan for agent-led purchasing?
Plan in stages and measure your own data. Allow agents to research and build baskets, apply your usual risk checks to anything they submit and treat the payment step as a separate, controlled moment. Review the results before extending more authority to agents.
Conclusion
The most useful thing in the current evidence is not a forecast. It is a pattern: attention to AI shopping is growing quickly, and willingness to hand over the payment lags willingness to hand over the research. The evidence for that pattern is thin, vendor-authored and North American, and it should be treated that way. For a merchant, the sensible response is to design delegation in steps, put clear controls at the point of payment and measure your own customers' behaviour rather than rely on anyone's forecast.